An office move puts a lot of value on the road at once: computers, servers, printers, furniture, files and stock. Most businesses insure their contents while they sit in the office, but fewer check what happens once those contents leave the building. Before you move, it is worth knowing exactly who covers what. This guide explains the main types of cover an office move needs, in plain terms, and the questions to ask before the day.
The three layers of cover
On most office moves, three kinds of insurance matter:
- Goods in transit cover, for loss of or damage to your items while they are being moved.
- Public liability insurance, held by the removal company, for injury to other people or damage to third-party property during the move.
- Your business’s own insurance, mainly your contents policy, and the cover you already hold as an employer.
None of these replaces the others. The aim is to make sure there are no gaps between them.
Goods in transit cover
Goods in transit cover protects your belongings from the moment they are loaded to the moment they are unloaded. It is the cover most people mean when they think about insuring a move.
With us, goods in transit cover of up to £50,000 per vehicle load is available to buy as part of your move. A few things to think about:
- Value per load. Add up roughly what each van will carry. IT equipment adds up fast. If one load would exceed the cover available, it may make sense to split the move across more loads or arrange extra cover through your own insurer.
- Who packed it. Some policies treat items packed by the customer differently from items packed by the crew. If you are packing yourself, ask how that affects any claim.
- Exclusions. Cash, data, personal items and some high-value pieces are often excluded or limited. Read the terms and ask about anything unusual.
- Excess. Check whether there is an excess on any claim.
Public liability insurance
Public liability covers the removal company if someone is injured or third-party property is damaged as a result of their work. On an office move, that might be a visitor tripping in a corridor, or a lift or shared entrance getting damaged by a trolley.
We hold public liability insurance of £1,000,000. Many landlords and building managers ask for proof of this before they will let a crew into a building, so ask your building manager early what they need and when.
Your business’s own insurance
Your own policies are the third layer. Before the move, ask your insurer or broker:
- Does our contents policy cover items while they are in transit, or only at our premises?
- Does it cover items in temporary storage, if we need it between buildings?
- Do we need to tell you the new address before the move, and from what date are we covered there?
- Does the move change our premium or any conditions?
If you have employees, you are generally required by law to hold employers’ liability insurance, and it needs to stay in place through the move. The gov.uk guide to employers’ liability insurance explains the rules. If staff are helping to pack or carry, make sure that is covered and that heavy lifting is left to the crew.
Reducing the risk in the first place
Insurance is there for when things go wrong. Good planning means you are less likely to need it. A well-run office move usually includes:
- A full inventory. List equipment with serial numbers and photos before packing.
- Data backups. Back up all data before any computer or server is moved. Data loss is rarely covered by moving insurance.
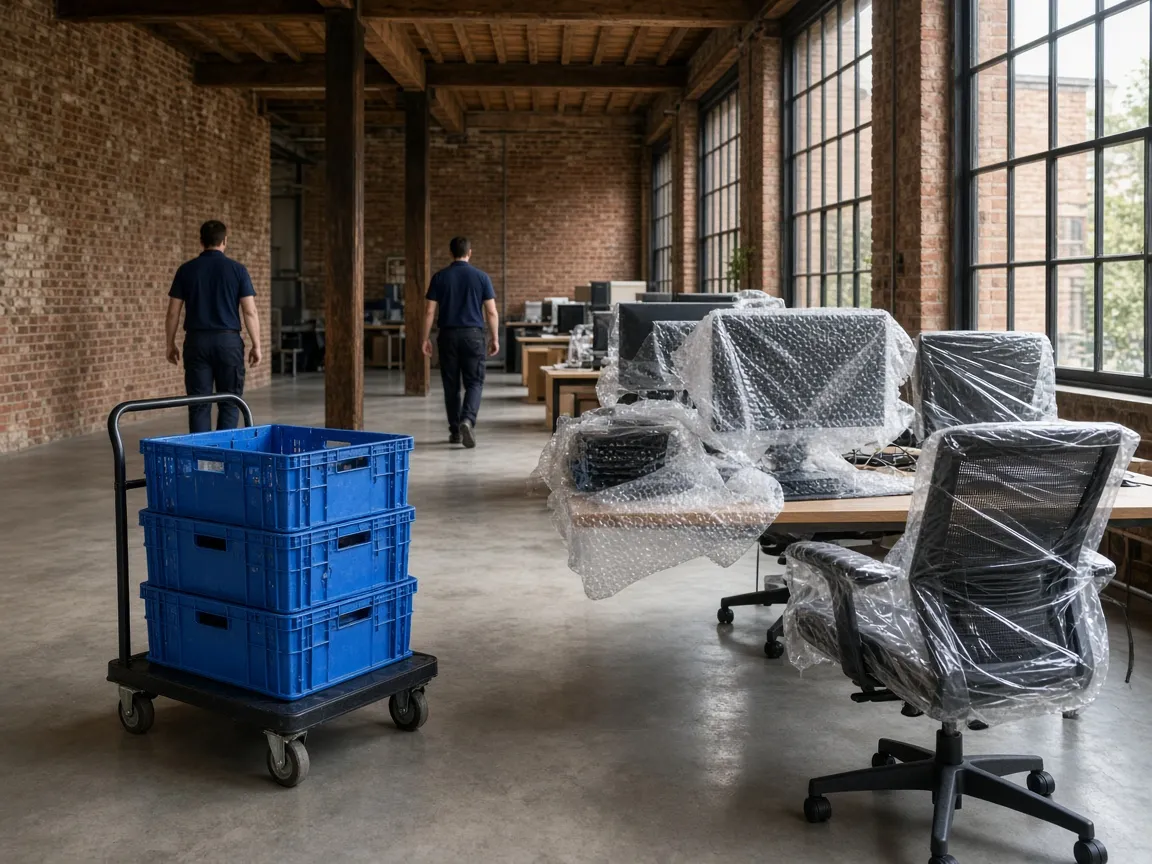
- Proper packing. IT equipment wrapped and crated, furniture protected, and files in sealed crates.
- Clear labelling. Each item coded to its place on the new floor plan, so nothing goes missing.
- Checks on arrival. Someone from your team checks items as they are unloaded and notes any damage straight away.
Our office removals team can help plan this, from packing to placing every desk.
A note on home moves
If you are also moving house, the cover you need is slightly different. Our guide to choosing insurance for a house move covers that side. For the wider planning of a business move, see our guide to moving office in Bradford.
Talk to us before you book
When you ask for a quote, tell us roughly what you are moving, what it is worth, and any building requirements on insurance. We will explain what cover is available and what you may want to arrange yourself. Get a free quote online or call 08000862860.
Planning a move in Bradford?
Get a free, no-obligation quote, or try the cost calculator for a rough idea first.